⚡ 30-Second Executive Briefing
- The 2026 Opportunity: US mortgage originations are projected to hit $2.2 trillion this year—an 8% increase—while lenders face rising expectations for “Explainable AI” in credit decisions.
- The Manila Solution: The Philippines has transitioned into a Global Intelligence Hub, where CPA-qualified “AI Orchestrators” manage autonomous agents to handle the bulk of routine underwriting, part of the lender and bank operations handled by Filipino specialists.
- Operational Impact: Lenders are achieving 48-hour “Time-to-Revenue” cycles and materially shortening DSO through “Atomic Reconciliation” and ISO 20022 data standards.
- Economic Advantage: Offshore delivery from Manila produces substantial operational savings, allowing mid-market lenders to deploy the same “10x Bank” technology as Tier-1 global institutions.
Executive Summary: The 2026 “Decisional Velocity” Race
In 2026, the global lending landscape is defined by the “10x Bank” philosophy—the vision where a single financial professional, empowered by Agentic AI, delivers the output of ten traditional employees. The bottleneck for lenders is no longer a lack of demand, but “Process Inertia.” With US refinance originations expected to surge by 9.2% to $737 billion this year, legacy manual loan processing systems are buckling under the weight of volume and regulatory scrutiny.
Loan processing outsourcing to the Philippines has evolved to solve this specific crisis. Moving far beyond legacy data entry, Manila’s financial BPO sector—projected to generate $42 billion in 2026 revenue—is now the primary driver for hyper-personalized lending. According toPITON-Global CEO John Maczynski, the 2026 model is about “Intelligence Arbitrage”: using $14–$16/hour specialists to govern autonomous systems that outperform domestic teams in both speed and accuracy. For lenders seeking the end-to-end modernization roadmap behind this underwriting evolution, consult the complete Financial Services Outsourcing Philippines (2026): A Strategic Blueprint.
Achieving “10x Loan Officer” Speed: The 2026 Philippine Strategy for High-Velocity Lending
In 2026, the $2.2 Trillion US Mortgage Market demands Explainable AI standards that legacy systems cannot meet. This strategy details the Manila Solution, where “AI Orchestrators” manage a 70% automated underwriting hub to deliver a 48-hour Time-to-Revenue. By moving to a Philippines Hybrid model, lenders slash Loan Approvals from 22 days to just 3–5 days and reduce KYC/AML processing to <24 hours. This operational pivot delivers 65–75% cost savings while keeping your institution “Compliance Ready” for model-risk and fair-lending reviews.
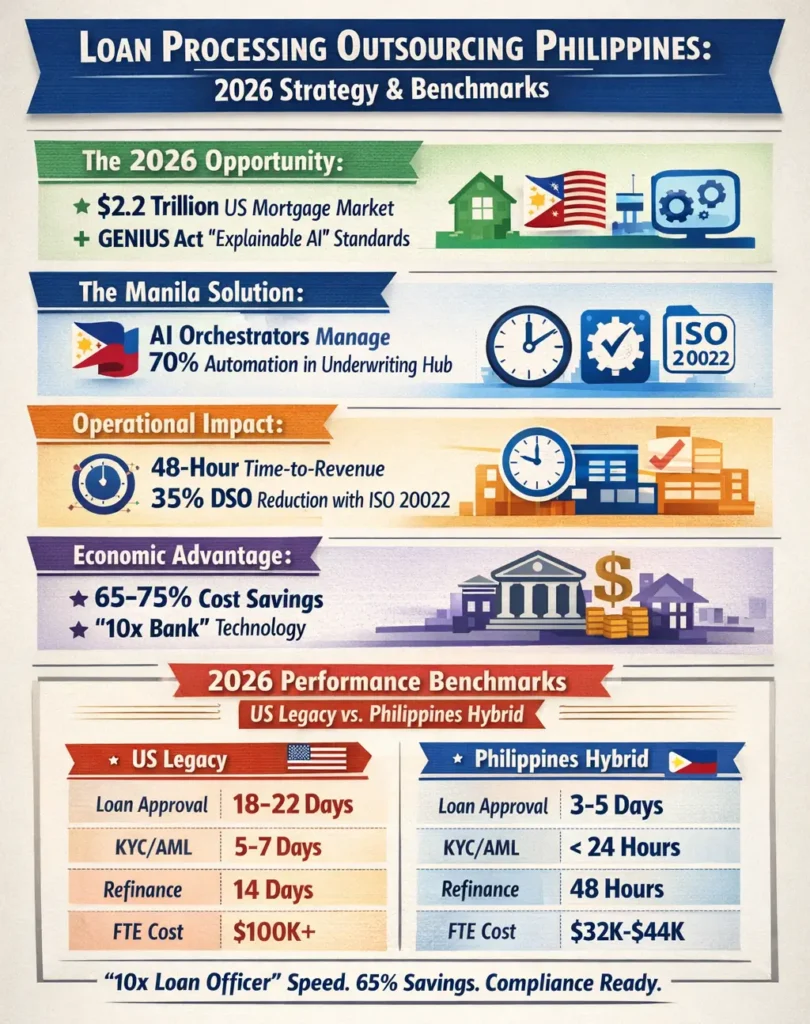
Traditional manual underwriting is anchored by high onshore FTE costs and 14-day cycles; this strategy deploys “10x Bank” Technology to reclaim margin. Utilizing ISO 20022 messaging, Manila hubs achieve sharp DSO reductions and 48-hour refinance speeds. With FTE costs stabilized at a fraction of onshore levels, this hybrid model ensures high-accuracy KYC/AML compliance, turning loan processing into a high-speed engine of Marketplace Liquidity.
The 2026 Compliance Moat: Explainable Credit Decisions
The demand for explainable AI has fundamentally changed the risk profile of offshore lending. Lenders need every AI-driven credit decision to be “Traceable and Auditable.” Traditional “Black Box” AI systems are no longer compliant, as lenders must now prove there is no “Discoverability Bias” in their automated funnels, the same audit-trail discipline behind outsourced regulatory reporting and model risk governance.
Elite Manila providers have responded by shifting from “Data Entry” to “Governance-as-a-Service.”
- AI Orchestrators: Manila-based staff now act as supervisors for autonomous agents, performing “Reasoning Path Audits” to ensure every loan denial or approval is backed by a compliant, documented rationale.
- Continuous Live State Compliance: Unlike the periodic audits of 2024, 2026 compliance is a “Live State.” Using Natural Language Processing (NLP), Filipino teams monitor 100% of borrower interactions and data ingestion points in real-time.
- Zero-Knowledge Enclaves: Sensitive borrower PII is handled within Sovereign Data Perimeters, satisfying 2026 SEC Cyber Resilience requirements. This ensures that while the intelligence is offshore, the data remains within the lender’s sovereign control.
Diving Deeper: The Rise of the “10x Loan Officer”
Industry benchmarks for 2026 highlight the emergence of a tiered hybrid model. As S&P Global predicts Non-QM loans will dominate 40% of non-agency issuance, the need for human nuance in “alt-doc” processing has never been higher.
Tier 1: Autonomous Underwriting (70% of Volume)
Standard applications (high-FICO, documented income) are now processed in under 3 seconds using Atomic Reconciliation. This removes the “grunt work” from the pipeline, allowing the system to handle the 5.8 million loans expected this year with zero domestic headcount increases.
Tier 2: Human-in-the-Loop (HITL) (30% of Volume)
The real value of the offshore team in 2026 lies in the “Exception Path.” When a “thin-file” borrower or a complex self-employed applicant triggers an AI alert, a Manila-based Risk Pilot intervenes. This prevents the “False Decline Problem” that currently costs US lenders billions in lost opportunities. These specialists are trained in Forensic Payment Analysis, looking for “human markers” and emotional context that even the most advanced 2026 AI cannot yet replicate.
2026 Comparative Performance Benchmarks: US vs. Philippines
| Performance Metric | Legacy In-House (US) | 2026 Philippine AI-Hybrid | Strategic Impact |
| KYC/AML Verification | 5–7 Days | < 24 Hours | Faster Onboarding |
| Loan Approval Cycle | 18–22 Days | 3–5 Days | 4.2x Pull-Through Lift |
| Refinance Processing | 14 Days | 48 Hours | Captures Rate-Drop Waves |
| Regulatory Accuracy | 94% | 99.9% | Zero “Buyback” Risk |
| Dispute Resolution | 18–30 Days | 7–12 Days | 60% Faster Cash Flow |
| Fully Loaded FTE Cost | $95k – $125k | $32k – $44k | 65%+ Operating Savings |
While achieving these benchmarks drastically improves front-end “Time-to-Revenue,” long-term EBITDA is often leaked through post-funding transaction friction. To prevent this, elite lenders are pairing their origination engines with a specialized Disputes & Chargebacks Management Outsourcing Philippines: 2026 Strategy to recover capital lost to automated claim cycles.
Reclaiming EBITDA: The Strategic CEO Perspective
The financial stakes of 2026 mean that human error in loan processing is no longer just a mistake; it is a structural risk to a company’s working capital. John Maczynski points out that in the current landscape, the goal of outsourcing is to buy back an internal team’s capacity for high-level capital allocation.
By utilizing Manila hubs that are fully integrated with ISO 20022 “rich data” standards, lenders achieve a “Continuous Close.” Transactions are reconciled as they clear in real-time, reducing the month-end close from a 10-day “scramble” to a 3-day verification process. This level of financial precision allows for agile, weekly financial forecasting that was previously impossible at scale.
Expert FAQ (2026 Executive Brief)
Q: How do Manila teams handle the 2026 “SEC Cyber Resilience” mandate?
A: Top-tier Manila BPOs utilize Biometric Desktop Monitoring and Hardware-Level Encryption at the agent level. Every interaction is logged within a Zero-Trust Sandbox, ensuring the 36-to-72-hour “Material Incident” reporting capabilities required by the SEC are consistently met.
Q: Can offshore teams manage “Non-QM” or DSCR loans?
A: Yes. Specialized “Alt-Doc” units in Manila are trained to audit bank statements and investment property cash flows that standard AI cannot yet fully parse. This is critical as Non-QM takes a growing share of the market.
Q: What is the impact of Agentic AI on staff tenure in Manila?
A: Tenure has increased to an industry-leading 34 months. By automating repetitive tasks, agents focus on high-level fraud forensics and complex multi-step disputes, which offers a more fulfilling and lucrative career path.
Securing Your Share of the Digital Economy
In 2026, loan processing is no longer a back-office function; it is a battle of intelligence. By leveraging the Philippines’ AI-powered, SEC-compliant infrastructure, lenders transform their “cost center” into a “profit engine.”
At PITON-Global, we provide the strategic bridge to ensure your lending vision thrives in this high-stakes environment. We can also build a customized ROI Projection Model for your specific loan volume.