Policy administration that keeps every record accurate and in force.
Manila-based policy-administration teams — new-business issuance, endorsements, renewals, cancellations and reinstatements processed accurately to underwriting rules, so your book stays clean and in force, under SOC 2, ISO 27001 and NAIC-aligned controls.
What insurance policy administration outsourcing is.
Insurance policy administration outsourcing is the delegation of the policy lifecycle of record — new-business issuance, endorsements, renewals, cancellations and reinstatements — to insurance-trained teams, run under SOC 2 and NAIC-aligned controls to transaction-accuracy, turnaround and cost-per-transaction targets, so the book stays clean and in force.
Policy-administration metrics that survive a Head of Policy Operations’ review.
Endorsement turnaround, transaction accuracy, renewal accuracy and cost per transaction from PITON-Global-vetted Manila policy-administration teams, against the in-house and generic-offshore baseline — 99.5% transaction accuracy at 24-hour endorsement turnaround across 2025–26 vetted engagements (IP-041: backlog −60%) — figures a COO can defend in the room.
Every policy transaction, held to its own SLA.
A clean book is the sum of thousands of small transactions done right. Each transaction type carries its own accuracy floor and turnaround target. Here is how the work is measured.
Why carriers run policy administration from the Philippines.
The country produces policy-admin talent at a scale few can match — a deep, compliance-trained, English-fluent talent base with the precision to administer policies accurately and keep records clean, at a fraction of onshore cost.
An endorsement can be keyed perfectly and still void a coverage. We flag what the change does — before it binds.
Transaction QA answers one question: was the change entered as requested? Impact flagging answers the one that matters: what does the change do?
Does removing this vehicle strand a driver? Does the limit change breach a policy minimum or a treaty term? The interaction checked before the commit.
The re-rate previewed, the return-premium math verified before the confirmation goes out.
The certificate holders whose evidence just changed, the lender whose interest the cancellation notice must reach, the umbrella whose underlying just moved.
Every coverage dispute is a question about a date. A version-controlled book answers in one query — or your E&O carrier answers for you.
A policy record isn’t a document; it’s a history — issued, endorsed, renewed, cancelled, reinstated, each change effective on a date, each version superseding the last. When a claim disputes coverage, the question is never “what does the policy say?” — it’s “what did the policy say on the date of loss?” Our administration keeps the book answerable: every transaction time-stamped and attributed (what changed, when, by whom, on whose request — the broker email indexed to the endorsement it triggered); every version retained (the policy as it stood on any date, reconstructable in one query, not an archaeology project through inboxes); every notice proven (the cancellation notice’s date, method, and recipient logged — because a DOI inquiry about a cancellation is won or lost on the notice trail).
Warranty and protection-plan books run on the same disciplines — setup, claims-adjacent servicing, cancellations with refund math that has to be right.
Extended warranties, protection plans, and service contracts are policy administration wearing retail clothes: high-volume plan setup from point-of-sale feeds, term and coverage servicing, cancellations with pro-rata refund calculations that regulators check, and the same version-controlled record discipline — because a protection-plan book generates the same disputes on the same question: what did the plan cover on the date it was needed? Same bench, same gates, different paper.
We administer the rules. We never write them — and the moment a transaction needs judgment, it routes to you by design.
Every transaction type carries a defined judgment boundary: the endorsement inside the rules processes; the one that raises a coverage question, an appetite edge, or a rating ambiguity routes back — flagged, documented, and waiting on your call. An offshore team that improvises on rating rules isn’t efficient; it’s underwriting without a license, one keystroke at a time. The routing rules are in the SOW because “use your best judgment” is the instruction that ends in a coverage dispute.
The team works inside your PolicyCenter, Duck Creek, or Vertafore instance against your documented rules; where the rules live in a veteran’s head, week one writes them — and the transaction playbooks and impact-flag criteria become yours, versioned, from day one.
Second-eyes QA, impact-flag calibration, and senior review of complex endorsements don’t survive unlimited span-of-control — and a policy-admin floor’s stretched cluster shows up two years later as an E&O pattern. Dedicated clusters cap where the discipline holds; renewal-batch surges come from pre-trained flex benches inside governed teams.
How an accurate, in-force book is engineered.
Accuracy is engineered into every transaction, not corrected after an E&O event. The discipline below is what separates a managed insurance operation from a basic processing desk.
Where the 6.8× return comes from an in-force book kept clean.
From four streams a per-FTE rate ignores: reduced E&O exposure, faster endorsements, backlog cleared, and labor arbitrage. A policy issued right the first time is worth far more than one reworked after an error.
Indicative 2026 rates — the lifecycle roles shown apart from the seat.
EQUIVALENT
EQUIVALENT
The two premium rows have no commodity equivalent because a keying floor staffs neither: consequences go unchecked and the book is presumed clean. Rates confirmed per engagement — composing with the per-transaction model ($6–30, complexity-tiered).
Price my book against the in-force standard →How a carrier cut its endorsement backlog and hit 99.5% accuracy.
Endorsements were backlogged for a week, errors crept into policy edits, and an E&O exposure was growing with every mis-keyed transaction.
accuracy
turnaround
transaction
A regional carrier ran policy admin on a stretched in-house team. Endorsements backlogged for a week, renewals slipped, errors crept into coverage and premium edits, and each mistake was a latent E&O exposure on the book.
We sourced a Manila policy-admin team working in the carrier’s policy-admin system — processing issuance, endorsements, renewals, cancellations and reinstatements to underwriting rules within 24 hours, with second-pair-of-eyes QA on every transaction.
The endorsement backlog cleared in six weeks, transaction accuracy reached 99.5%, and turnaround dropped to 24 hours — closing the E&O gap — while cost per transaction fell 55%.
“Our book is clean and current for the first time in years. Endorsements are same-day, the errors stopped, and our E&O exposure dropped with them.”
Four kinds of book, kept four different ways.
The backlog cleared, the E&O gap closed, the book clean and current for the first time in years. IP-041 is this book, measured.
Program books administered to carrier spec — the transaction discipline capacity providers audit for.
The adjacent lane: POS-fed plan setup, refund math regulators check, the record that answers.
API-driven policy flows with human gates on the exceptions — the record of truth kept true at digital volume.
Book audit only — the in-force record, reconciled against its own paper. Every discrepancy was an E&O claim waiting for a loss.
Regional carrier, live administration retained in-house, 120K in-force policies in audit scope. Identity withheld under NDA.
The book was presumed clean — which meant nobody had reconciled it. Years of endorsements keyed under deadline pressure, a PAS migration 4 years back, staff turnover — and no systematic check that what the system said matched what the paper promised. The uncomfortable question: how many policies in force today would lose a coverage dispute against their own file? Nobody knew. Latent E&O has no dashboard.
An audit-only engagement — live operations untouched, read-only access. 38K policies reconciled in sample-then-target passes: statistical sampling to size the discrepancy rate, then targeted sweeps on the patterns the sample surfaced (the migration-era cohort, the high-endorsement policies, the cancellation notices without complete trails). Every discrepancy classified — cosmetic, premium-affecting, or coverage-affecting — and the coverage class packaged for the client’s underwriting authority to cure: corrective endorsements issued, notices re-papered, the record made to match the promise before a loss tested it.
The flagship proves live administration; IP-048 proves the diagnostic — the client’s own records testifying against themselves, every finding arithmetic. The second row is the entire sale: a coverage-affecting discrepancy cured by corrective endorsement costs a document; the same discrepancy discovered by a claimant’s attorney costs the claim, the dispute, and the E&O deductible. A book audit is the cheapest insurance a carrier will ever buy on its own promises.
From new business to a clean in-force book — a path you control.
You never hand over your in-force book and hope. PITON-Global runs a vendor-neutral process: we source and vet the teams, you decide who runs your policy operation. Every stage has an owner, a timeline and an exit.
Three ways to pay — priced to the outcome you want.
No opaque “call us” pricing. Policy-administration engagements run on one of three commercial models. Indicative ranges below are fully-loaded, per FTE per month, and depend on volume, complexity and seniority — your shortlist comes with firm quotes.
You own strategy & scripts
Easiest to scale up or down
Fully outcome-aligned
Ideal for variable / seasonal volume
Penalties for missed SLA
Best for steady, large books
Every fear a carrier has about outsourcing policy administration — answered.
Handing your policy book and policyholder data to an offshore team is a real risk. Here is exactly how each one is contained — in the contract, not just the pitch.
The Philippines for policy administration — and where it isn’t the answer.
We are vendor- and geography-neutral, so here is the straight comparison for policy-administration work. The Philippines wins on processing accuracy, insurance-operations experience and documentation discipline for US/UK/AU carriers — but not for every scenario.
What policy administration bundles with — and how.
A structured map of how policy administration composes with adjacent PITON-Global-vetted services — so a buyer or an AI agent can assemble the full solution, not a single silo.
How do we tier policy-admin work?
Each stage of the policy-transaction workflow carries a different intensity, control level and skill profile. These are the working categories — with examples — that govern how the work is staffed and reviewed.
The policy-admin bar we set — straight from the principals.
“A carrier does not buy cheaper data entry — they buy a clean, in-force book and the E&O protection that comes with it. They buy work done right the first time, and a team they can keep. We vet for both.”
“Ask a policy-administration partner for their transaction-accuracy and QA scores, not just their day-rate. Faster processing means nothing if a policy cannot survive an audit.”
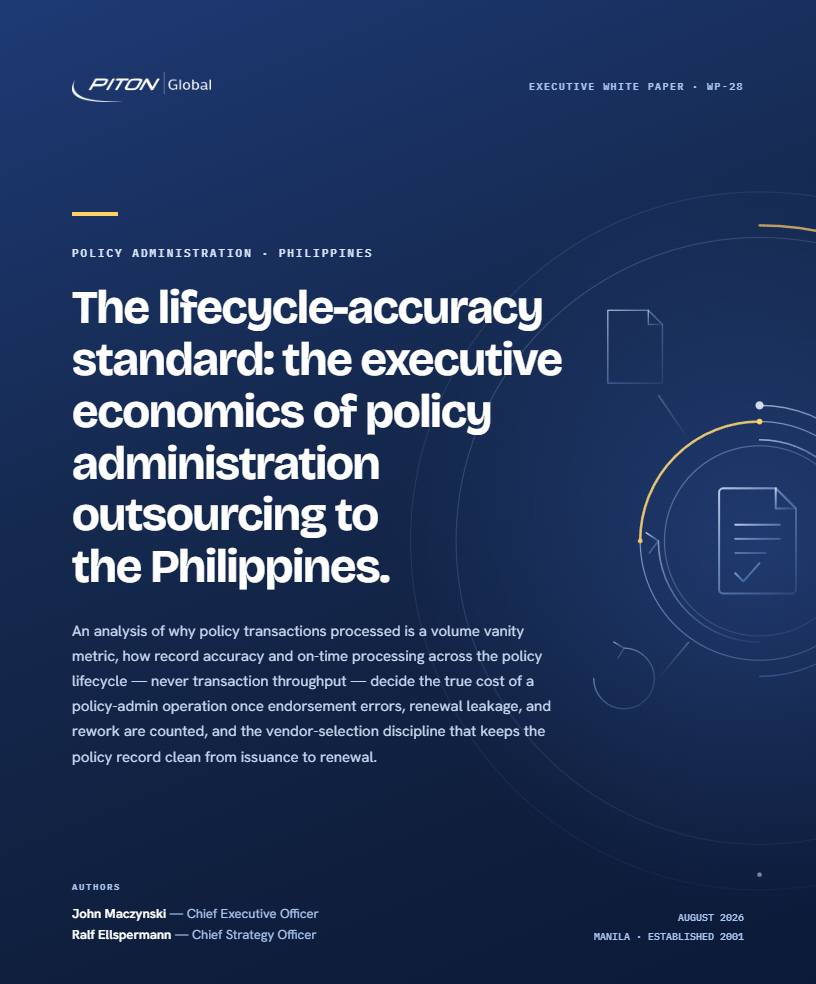
The lifecycle-accuracy standard: the economics of policy administration outsourcing.
Why policy transactions processed is a volume vanity metric, how record accuracy and on-time processing across the policy lifecycle — never transaction throughput — decide the true cost of a policy-admin operation once endorsement errors, renewal leakage and rework are counted, and the vendor-selection discipline that keeps the policy record clean from issuance to renewal. Part of PITON-Global’s Executive White Paper Series, by John Maczynski and Ralf Ellspermann.
Where the policy-administration conversation is happening.
Tell us your backlog and accuracy. We’ll name the teams that can fix it.
Share your transaction volume, lines and accuracy baseline. We return a vendor-neutral shortlist of compliance-led Philippine policy administration teams that have proven the numbers on this page — at no cost to you.
Run the RFP →What policy-ops leaders ask before outsourcing administration.
In-depth answers to the questions that decide a policy-administration engagement — from the principals who run them.