
How do we know an insurance BPO is actually insurance-literate before we sign?
Test it live. Ask three agents to complete an ACORD 125 on a real commercial submission, explain scheduled versus blanket coverage, and handle a late notice of loss at FNOL. In our Q2 2026 audits, 69% of providers claiming insurance capability failed that test, and 61% had no separate protocol for catastrophic claims.
Put three agents in front of a commercial submission and ask for a completed ACORD 125, the difference between scheduled and blanket coverage, and how they’d handle late notice at FNOL — 69% of providers claiming insurance capability failed that live evaluation, and 61% had no separate protocol for catastrophic claims. The regional insurer proves the dual-track carrier architecture; the growing insurtech platform: FNOL accuracy 89.3% to 99.5%, rework 24% to 3.1%.
BPO Suppliers
MGAs Served
Delivering for Clients
In 2026, insurance leaders aren’t just looking for cost savings — they are looking for Regulatory Resilience. The Philippines has become a strategic extension of the carrier, where Agentic AI and human empathy converge to eliminate claims backlogs, deliver 99.5% FNOL accuracy and accelerate underwriting velocity by 2.4×.
What do insurers outsource to the Philippines first?
Carriers usually move policyholder service first: billing and coverage questions, FNOL intake, renewals and enrollment-season surges. Claims intake follows, then policy administration and underwriting support. Starting with policyholder service gives the team product and platform fluency on the function policyholders judge you by, before it takes on claims and underwriting files.
How do lines of business and platform shape an insurance outsourcing program?
P&C carriers need FNOL triage and surge capacity for catastrophe peaks. Life and health carriers need admin-only servicing under HITRUST CSF, with no clinical determinations. Brokers, MGAs and agencies need submission and COI administration, and insurtechs need platform operations that keep pace with the book. Guidewire, Duck Creek or Applied Epic access is the starting point.
Auto, property, GL, commercial, and specialty programs — where FNOL volume meets catastrophe peaks. Agentic FNOL Triage at 99.5% capture, SIU-ready fraud scoring, and surge capacity that doesn’t cost you accuracy in CAT season.
Policy servicing, beneficiary changes, and non-clinical claims coordination — administered under HITRUST CSF with non-persistent VDI for all PHI. No clinical determinations, ever; that boundary is the moat. Includes medical records retrieval: attending physician statements for life underwriting and medical records for disability and claims files.
ANCHORS TOThe Compliance Moat →Carrier-submission administration, COI processing, and policy-servicing back-office — pre-analyzed files that lift quote turnaround 2.4× and broker win rates with it.
Platform operations, policy-lifecycle administration, and 24/7 follow-the-sun ticket handling for books that grow faster than back-office capacity. Scale governed, not improvised.
Why do surging claims volumes and tightening oversight create a paradox traditional BPO cannot resolve?
Because speed and accuracy pull against each other: rushing FNOL intake drops accuracy, and slowing down for accuracy drops velocity. Agentic FNOL Triage breaks the trade-off by scoring severity, verifying coverage and flagging fraud in the first 90 seconds, delivering 99.5% FNOL accuracy and 32% faster resolution at the same time.
Because prioritizing speed drops FNOL accuracy, and prioritizing accuracy drops velocity — and traditional BPO can only buy one at the cost of the other. Agentic FNOL Triage breaks the trade-off, delivering 99.5% FNOL accuracy and 32% faster resolution simultaneously by removing the manual processing bottleneck entirely.
Agentic FNOL Triage is an AI orchestration layer that autonomously scores claim severity, verifies policy coverage in real time against Guidewire, Duck Creek or Applied Epic, and flags fraud indicators within the first 90 seconds of first notice of loss — routing only judgment-critical exceptions to human specialists.
“The operations we vet are not generic BPOs that have added an insurance vertical. They are claims and policy administration specialists audited under HITRUST CSF and NAIC-aligned standards — operating at a higher level of both speed and accuracy simultaneously. That is not a marginal improvement. It is a structural advantage.”
How does a dual-track claims and underwriting model work?
Agentic Claims Operations and Predictive Underwriting Support run at the same time in one HITRUST-governed data environment. Claims data quality feeds underwriting risk modeling, and better underwriting reduces claims frequency. A human empathy layer handles what AI cannot, such as total-loss notifications and catastrophic claims, where a scripted response creates bad-faith exposure.
Agentic Claims Operations and Predictive Underwriting Support run simultaneously — claims data quality feeds underwriting risk modeling, and underwriting accuracy reduces claims frequency. The empathy layer handles what AI cannot.
Fraud scoring runs on the platforms carriers already license, such as Shift Technology, FRISS, FICO Insurance Fraud Manager and NICE Actimize, with Philippine fraud analysts providing contextual review and escalation.
When the policyholder is on the phone, the staffing, service-level and telephony rules that govern any voice floor still apply, and our guide to call center outsourcing in the Philippines covers them; the empathy and licensing boundary described here sits on top.
AI performs severity scoring, real-time policy verification and fraud-signal detection in the first 90 seconds of first notice of loss. Human specialists own the judgment-critical support work: preparing and documenting contested-coverage files, assembling complex-liability records, and delivering sensitive loss notifications — with every coverage determination and claims decision escalated to and made by the carrier’s licensed adjusters. Native to Guidewire and Duck Creek.
“The single most reliable ROI driver is underwriting support delegation. An underwriter earning $180K who spends 48% of their time collecting risk data is generating $86K of insurance-literate admin work a Philippine specialist delivers at 15% of the cost — and returning $94K of underwriting judgment capacity no admin support can replicate.”
Where does the efficiency dividend in insurance outsourcing come from?
For a 25-agent insurance team it has five parts: $0.9M–$1.2M in direct labor savings, 60% higher underwriter productivity with 2.4× quote turnaround, 86% less rework at 99.5% FNOL accuracy, a CSAT-driven renewal lift from 78% to 89%, and the compliance moat of HITRUST CSF and NAIC-aligned governance.
Three components every ROI model captures — labor savings, underwriter productivity, CSAT-driven renewal uplift — and one it consistently misses: the compliance moat. Operating under HITRUST CSF and NAIC-aligned governance when competitors are not is the component that determines long-term market position.
How much does insurance outsourcing to the Philippines cost?
At 1,920 paid hours a year, a fully loaded US onshore insurance-operations FTE costs about $69,000 ($36 an hour). A Philippine global-BPO seat runs about $31,000 ($16 an hour), and a PITON-Global-vetted, ACORD-screened, HITRUST-governed seat about $23,000 ($12 an hour). Labor is the largest line a CFO sees but the smallest part of the dividend.
Direct labor savings is the “PRIMARY” bar above, so we publish its arithmetic. Then note what the chart already told you: three of the five dividend components never appear on a seat invoice.
The seat lens prices the agent. The Efficiency Dividend prices the operation. Illustrative projection at standard role mix; labor savings run 50–70% depending on the ratio of specialist roles to servicing volume. We confirm exact figures — labor line and full dividend — against your lines of business, claim volumes, and core platform.
What are the 2026 rates for insurance roles in the Philippines?
Indicative 2026 rates are $10–$14 an hour for policy administration specialists, billing and renewals specialists and insurance CX specialists, published as bands rather than one blended rate. A quote well below the band is how buyers end up with agents who cannot complete an ACORD 125, which describes 69% of the providers we audited.
We publish the bands because the Domain Gap has a price signature. Insurance-literate, ACORD-proficient specialists price inside these ranges. A quote materially below band is how you buy an agent who cannot complete an ACORD 125 — 69% of the Q2 2026 PITON-Global insurance audit cohort (n=100) — and the NIGO rate, rework multiple, and DOI exposure that come with them.
Every band assumes the specialist passed ACORD proficiency testing, US terminology assessment, and lines-of-business training before deployment — the Insurance-Literate Hiring standard. Rates confirmed per engagement against role mix and platform. Rates are for mid-sized providers that specialize in insurance work, not generalist call centers. PITON-Global projects 2027 rates about $2 an hour higher at each end of every band, as AI absorbs routine work and pay and inflation rise.
Price my role mix against the ACORD standard →How do vetted Philippine insurance BPOs compare with legacy providers?
Against a legacy 2024 baseline, the PITON-Global-vetted 2026 standard responds in under 15 minutes instead of 2–4 hours, captures FNOL at 99.5% accuracy instead of 88–92%, catches 95.8% of FNOL fraud instead of 69%, and cuts downstream rework from 22–28% of claims to 3.1%.
The competitive delta between a legacy 2024 BPO baseline and the PITON-Global-vetted 2026 standard — across nine dimensions that determine accuracy, velocity and regulatory certainty.
How a regional carrier turned claims accuracy into a $2.8M dividend.
A documented Q4 2025 engagement: a US regional carrier processing 8,400 monthly claims across commercial property, casualty and personal lines, deploying a 25-specialist Philippine operations team under HITRUST CSF governance.
One track, one growth curve — an insurtech deployment, measured.
The flagship engagement proves the dual-track carrier architecture; The regional insurer proves the dual-track carrier architecture; the growing insurtech platform proves the entry point. An insurtech does not need a claims transformation to stop drowning — a governed servicing track, scaled ahead of the growth curve instead of behind it, cleared the backlog in one quarter with the claims stack untouched. The architecture scales down to the size of the strain.
Our previous Philippine BPO processed total loss notifications through the same agent queue as routine claims inquiries. Our DOI complaint rate for total loss claims was 4.2 per 1,000. The Claims Empathy Specialist protocol PITON-Global specified reduced that to 0.6 per 1,000 in 90 days. The FNOL accuracy gain was significant — but the empathy architecture was what moved the needle on regulatory exposure.
Two structural failure modes that no SLA clause can remediate.
The Domain Gap and the Empathy Deficiency account for the majority of insurance outsourcing failures in 2026. Both generate regulatory exposure and policyholder harm that no efficiency saving can offset. Both are auditable before contract execution.
When is insurance outsourcing to the Philippines the wrong fit?
When you want bulk keying at the lowest seat-hour, when there is no core platform such as Guidewire, Duck Creek or Applied Epic to integrate with, or when the work needs a licensed decision. No vetted team adjusts claims, makes coverage determinations or renders underwriting decisions; those stay with your licensed adjusters and underwriters.
The fastest way to become one of the 2026 failure statistics is to force a high-judgment, HITRUST-governed insurance operation into work it was never built for. So before the shortlist, the disqualifiers — ours, stated plainly.
Insurance-literate talent density, ACORD-proficiency screening, and Claims Empathy Specialist protocols do not survive unlimited scale. Vetted partner operations are capped per cluster to guarantee management control, compliance oversight, and the judgment quality the work depends on. If your volume requires more, we architect multiple governed clusters — we do not dilute one.
Why building regulatory architecture before enforcement is insurance’s most undervalued decision.
The NAIC Insurance Data Security Model Law has been adopted in 24 states as of Q2 2026, with enforcement momentum accelerating. Carriers whose Philippine operations already run under NAIC-aligned governance — HITRUST CSF, continuous compliance telemetry, Non-Persistent VDI for all PHI — are not just compliant today. They are positioned ahead of the curve that will force competitors into expensive remediation within 18–24 months.
The moat has commercial value: a carrier demonstrating NAIC-aligned governance wins RFPs from institutional and reinsurance partners who now include data governance in cedent evaluation. Lloyd’s syndicates, global reinsurers and captive managers increasingly require evidence of NAIC-aligned controls in counterparty due diligence.
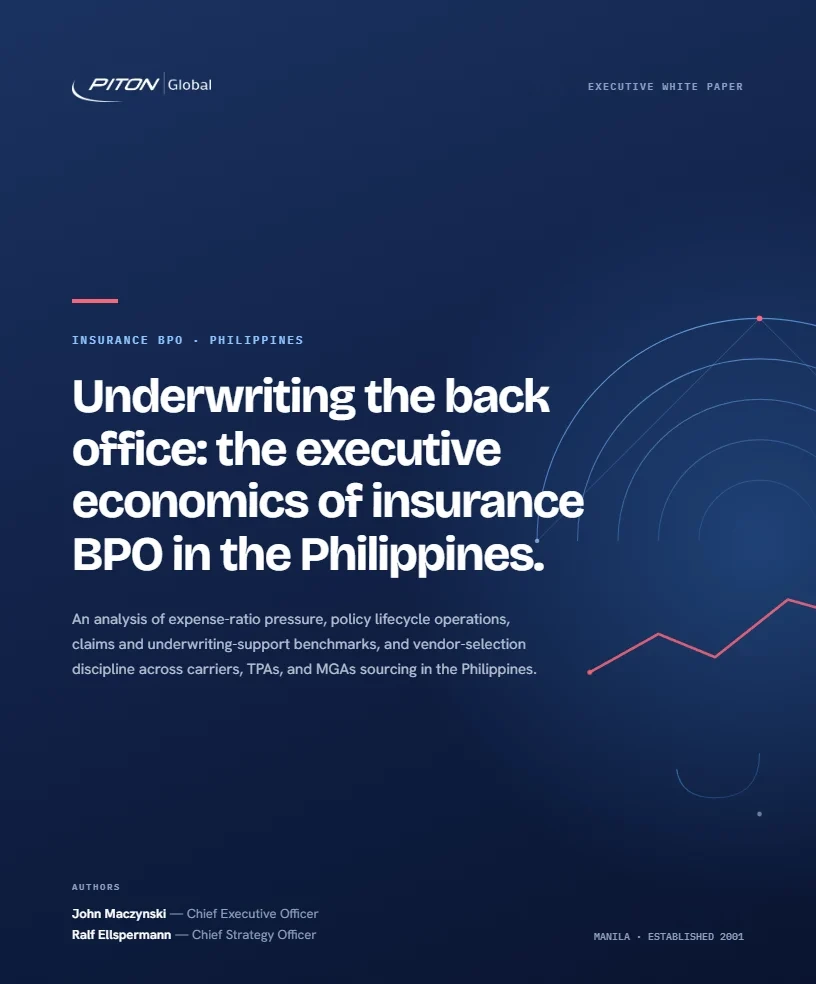
Underwriting the Back Office — Insurance BPO in the Philippines
An analysis of expense-ratio pressure, policy lifecycle operations, claims and underwriting-support benchmarks, and vendor-selection discipline across carriers, TPAs, and MGAs sourcing in the Philippines. Part of PITON-Global’s Executive White Paper Series, by John Maczynski and Ralf Ellspermann.
Meet the insurers’ BPOs that survived the audit.
Out of the entire Philippine market, only a handful clear every gate we set: the ACORD proficiency audit, the HITRUST CSF certification review, the Claims Empathy Specialist protocol, and a live FNOL accuracy assessment scored on real first-notice calls. The ones that pass carry zero domain gaps and zero empathy deficiency — and those are the only names we hand you.
Get Vendor-Neutral Advice →Our 24-Hour Response Guarantee — a reply within 24 hours, ACORD and HITRUST pre-screen included.
What insurance leaders ask before outsourcing claims and policy admin.
In-depth answers to the questions that decide an insurance BPO engagement — from the principals who run them.

Going deeper on insurance operations
Insurance is one of the most specialized verticals in the market, and this page sits inside our broader guide to outsourcing to the Philippines, which explains how the delivery model works before any single line of business adds its own rules. The pages below are our longer reading on insurance outsourcing, grouped by the decision each one helps a carrier, MGA or broker make. Read them in the order your program will meet them: claims first for most buyers, then the regulatory and seasonal questions, then technology.
Claims, from first notice to settlement
Claims is usually the first queue to move, and the one where a weak vendor does the most damage. Define what the offshore team prepares and what your licensed adjusters decide, write maker-checker points into the SOP, and measure accuracy and leakage before speed. A clean parallel run on your own platform matters more than any benchmark a vendor quotes.
For the operating detail, start with how claims processing and adjudication support is run offshore, then read how digital intake is changing claims handling and the insurtech angle on claims operations.
Life, health and enrollment-season staffing
Life and health books run on a calendar, and staffing has to follow it. Plan the enrollment surge months ahead, keep a trained core team through the quieter months so quality survives the peak, and make sure every agent script has been reviewed against federal marketing rules before the first call.
Our guide to staffing L&H agents beyond the annual enrollment window covers the year-round model, and what is reshaping open-enrollment staffing in 2026 covers the surge itself. When underwriting or claims files are waiting on physician records, see how medical records retrieval teams handle authorizations, provider outreach and complete charts. On the regulatory side, read how CMS and TPMO rules shape a compliant voice operation. Health-adjacent programs should also look at our healthcare hub for the HIPAA and PHI side of the work.
Compliance, governance and continuity
Regulators judge the carrier, not the vendor, so governance has to be something you can evidence on demand. Ask for the audit trail on a live file, confirm how policyholder data is contained, and test the continuity plan before you need it rather than after a typhoon or outage forces the question.
Read the governance model for regulated insurance work first.
Policyholder service and the front office
Servicing is where a carrier’s brand is felt, so train for your tone and products, calibrate QA across every channel, and route sensitive conversations to the people trained to handle them. Our piece on delivering front-office insurance service sets out the model, and how insurance back-office and CX teams are vetted covers the servicing roles, rates and controls behind it.
Technology, AI and risk data
Automation now handles much of the intake and data work, which makes the question where a human must review and who signs. Ask vendors to show that hand-off on a real file, native to your core system, and to explain how exceptions escalate.
How risk assessment support has been rebuilt covers the underwriting side.
Travel and specialty claims
Specialty lines bring their own partners and deadlines. Travel cover sold through booking platforms, for example, needs claims teams that understand both the policy and the trip.
The market and the model
If you are still deciding whether the model fits, four overview pieces set the context: why Manila became a center for insurance operations, how the scope of offshore insurance work has widened, the growth of the sector as a whole and the range of roles Filipino teams now fill for carriers.
What it costs
The rate bands above are the starting point, but the real number depends on your role mix, lines of business and how much of the queue automation absorbs. Our pricing page and savings calculator shows the fully loaded model we use and explains where savings grow and where they flatten.
Choosing a vendor
Many providers claim an insurance vertical; far fewer pass an audit built for one. Our seven-step vendor vetting framework is the method behind every insurance BPO shortlist we build, from scope analytics through forensic diligence to launch governance, and the shortlist is free and carries no obligation. Carriers with banking or lending affiliates can compare notes on the financial services hub.
How do we know an insurance BPO is actually insurance-literate before we sign?
Test it live. Ask three agents to complete an ACORD 125 on a real commercial submission, explain scheduled versus blanket coverage, and handle a late notice of loss at FNOL. In our Q2 2026 audits, 69% of providers claiming insurance capability failed that test, and 61% had no separate protocol for catastrophic claims.
Put three agents in front of a commercial submission and ask for a completed ACORD 125, the difference between scheduled and blanket coverage, and how they’d handle late notice at FNOL — 69% of providers claiming insurance capability failed that live evaluation, and 61% had no separate protocol for catastrophic claims. The regional insurer proves the dual-track carrier architecture; the growing insurtech platform: FNOL accuracy 89.3% to 99.5%, rework 24% to 3.1%.
BPO Suppliers
MGAs Served
Delivering for Clients
In 2026, insurance leaders aren’t just looking for cost savings — they are looking for Regulatory Resilience. The Philippines has become a strategic extension of the carrier, where Agentic AI and human empathy converge to eliminate claims backlogs, deliver 99.5% FNOL accuracy and accelerate underwriting velocity by 2.4×.
What do insurers outsource to the Philippines first?
Carriers usually move policyholder service first: billing and coverage questions, FNOL intake, renewals and enrollment-season surges. Claims intake follows, then policy administration and underwriting support. Starting with policyholder service gives the team product and platform fluency on the function policyholders judge you by, before it takes on claims and underwriting files.
How do lines of business and platform shape an insurance outsourcing program?
P&C carriers need FNOL triage and surge capacity for catastrophe peaks. Life and health carriers need admin-only servicing under HITRUST CSF, with no clinical determinations. Brokers, MGAs and agencies need submission and COI administration, and insurtechs need platform operations that keep pace with the book. Guidewire, Duck Creek or Applied Epic access is the starting point.
Auto, property, GL, commercial, and specialty programs — where FNOL volume meets catastrophe peaks. Agentic FNOL Triage at 99.5% capture, SIU-ready fraud scoring, and surge capacity that doesn’t cost you accuracy in CAT season.
Policy servicing, beneficiary changes, and non-clinical claims coordination — administered under HITRUST CSF with non-persistent VDI for all PHI. No clinical determinations, ever; that boundary is the moat. Includes medical records retrieval: attending physician statements for life underwriting and medical records for disability and claims files.
ANCHORS TOThe Compliance Moat →Carrier-submission administration, COI processing, and policy-servicing back-office — pre-analyzed files that lift quote turnaround 2.4× and broker win rates with it.
Platform operations, policy-lifecycle administration, and 24/7 follow-the-sun ticket handling for books that grow faster than back-office capacity. Scale governed, not improvised.
Why do surging claims volumes and tightening oversight create a paradox traditional BPO cannot resolve?
Because speed and accuracy pull against each other: rushing FNOL intake drops accuracy, and slowing down for accuracy drops velocity. Agentic FNOL Triage breaks the trade-off by scoring severity, verifying coverage and flagging fraud in the first 90 seconds, delivering 99.5% FNOL accuracy and 32% faster resolution at the same time.
Because prioritizing speed drops FNOL accuracy, and prioritizing accuracy drops velocity — and traditional BPO can only buy one at the cost of the other. Agentic FNOL Triage breaks the trade-off, delivering 99.5% FNOL accuracy and 32% faster resolution simultaneously by removing the manual processing bottleneck entirely.
Agentic FNOL Triage is an AI orchestration layer that autonomously scores claim severity, verifies policy coverage in real time against Guidewire, Duck Creek or Applied Epic, and flags fraud indicators within the first 90 seconds of first notice of loss — routing only judgment-critical exceptions to human specialists.
“The operations we vet are not generic BPOs that have added an insurance vertical. They are claims and policy administration specialists audited under HITRUST CSF and NAIC-aligned standards — operating at a higher level of both speed and accuracy simultaneously. That is not a marginal improvement. It is a structural advantage.”
How does a dual-track claims and underwriting model work?
Agentic Claims Operations and Predictive Underwriting Support run at the same time in one HITRUST-governed data environment. Claims data quality feeds underwriting risk modeling, and better underwriting reduces claims frequency. A human empathy layer handles what AI cannot, such as total-loss notifications and catastrophic claims, where a scripted response creates bad-faith exposure.
Agentic Claims Operations and Predictive Underwriting Support run simultaneously — claims data quality feeds underwriting risk modeling, and underwriting accuracy reduces claims frequency. The empathy layer handles what AI cannot.
Fraud scoring runs on the platforms carriers already license, such as Shift Technology, FRISS, FICO Insurance Fraud Manager and NICE Actimize, with Philippine fraud analysts providing contextual review and escalation.
When the policyholder is on the phone, the staffing, service-level and telephony rules that govern any voice floor still apply, and our guide to call center outsourcing in the Philippines covers them; the empathy and licensing boundary described here sits on top.
AI performs severity scoring, real-time policy verification and fraud-signal detection in the first 90 seconds of first notice of loss. Human specialists own the judgment-critical support work: preparing and documenting contested-coverage files, assembling complex-liability records, and delivering sensitive loss notifications — with every coverage determination and claims decision escalated to and made by the carrier’s licensed adjusters. Native to Guidewire and Duck Creek.
Senior underwriters spend 40–55% of their time on insurance-literate administrative work — risk-data collection, ACORD forms, exposure analysis — that requires no underwriting judgment. Delegating it returns that capacity to the decisions only the underwriter can make. Quote prep collapses from hours to minutes.
The specialist owns the conversation; the carrier’s licensed professional owns the decision. That boundary is not a limitation — it is the compliance moat.
“The single most reliable ROI driver is underwriting support delegation. An underwriter earning $180K who spends 48% of their time collecting risk data is generating $86K of insurance-literate admin work a Philippine specialist delivers at 15% of the cost — and returning $94K of underwriting judgment capacity no admin support can replicate.”
Where does the efficiency dividend in insurance outsourcing come from?
For a 25-agent insurance team it has five parts: $0.9M–$1.2M in direct labor savings, 60% higher underwriter productivity with 2.4× quote turnaround, 86% less rework at 99.5% FNOL accuracy, a CSAT-driven renewal lift from 78% to 89%, and the compliance moat of HITRUST CSF and NAIC-aligned governance.
Three components every ROI model captures — labor savings, underwriter productivity, CSAT-driven renewal uplift — and one it consistently misses: the compliance moat. Operating under HITRUST CSF and NAIC-aligned governance when competitors are not is the component that determines long-term market position.
How much does insurance outsourcing to the Philippines cost?
At 1,920 paid hours a year, a fully loaded US onshore insurance-operations FTE costs about $69,000 ($36 an hour). A Philippine global-BPO seat runs about $31,000 ($16 an hour), and a PITON-Global-vetted, ACORD-screened, HITRUST-governed seat about $23,000 ($12 an hour). Labor is the largest line a CFO sees but the smallest part of the dividend.
Direct labor savings is the “PRIMARY” bar above, so we publish its arithmetic. Then note what the chart already told you: three of the five dividend components never appear on a seat invoice.
The seat lens prices the agent. The Efficiency Dividend prices the operation. Illustrative projection at standard role mix; labor savings run 50–70% depending on the ratio of specialist roles to servicing volume. We confirm exact figures — labor line and full dividend — against your lines of business, claim volumes, and core platform.
What are the 2026 rates for insurance roles in the Philippines?
Indicative 2026 rates are $10–$14 an hour for policy administration specialists, billing and renewals specialists and insurance CX specialists, published as bands rather than one blended rate. A quote well below the band is how buyers end up with agents who cannot complete an ACORD 125, which describes 69% of the providers we audited.
We publish the bands because the Domain Gap has a price signature. Insurance-literate, ACORD-proficient specialists price inside these ranges. A quote materially below band is how you buy an agent who cannot complete an ACORD 125 — 69% of the Q2 2026 PITON-Global insurance audit cohort (n=100) — and the NIGO rate, rework multiple, and DOI exposure that come with them.
Every band assumes the specialist passed ACORD proficiency testing, US terminology assessment, and lines-of-business training before deployment — the Insurance-Literate Hiring standard. Rates confirmed per engagement against role mix and platform. Rates are for mid-sized providers that specialize in insurance work, not generalist call centers. PITON-Global projects 2027 rates about $2 an hour higher at each end of every band, as AI absorbs routine work and pay and inflation rise.
Price my role mix against the ACORD standard →How do vetted Philippine insurance BPOs compare with legacy providers?
Against a legacy 2024 baseline, the PITON-Global-vetted 2026 standard responds in under 15 minutes instead of 2–4 hours, captures FNOL at 99.5% accuracy instead of 88–92%, catches 95.8% of FNOL fraud instead of 69%, and cuts downstream rework from 22–28% of claims to 3.1%.
The competitive delta between a legacy 2024 BPO baseline and the PITON-Global-vetted 2026 standard — across nine dimensions that determine accuracy, velocity and regulatory certainty.
How a regional carrier turned claims accuracy into a $2.8M dividend.
A documented Q4 2025 engagement: a US regional carrier processing 8,400 monthly claims across commercial property, casualty and personal lines, deploying a 25-specialist Philippine operations team under HITRUST CSF governance.
One track, one growth curve — an insurtech deployment, measured.
The flagship engagement proves the dual-track carrier architecture; The regional insurer proves the dual-track carrier architecture; the growing insurtech platform proves the entry point. An insurtech does not need a claims transformation to stop drowning — a governed servicing track, scaled ahead of the growth curve instead of behind it, cleared the backlog in one quarter with the claims stack untouched. The architecture scales down to the size of the strain.
Our previous Philippine BPO processed total loss notifications through the same agent queue as routine claims inquiries. Our DOI complaint rate for total loss claims was 4.2 per 1,000. The Claims Empathy Specialist protocol PITON-Global specified reduced that to 0.6 per 1,000 in 90 days. The FNOL accuracy gain was significant — but the empathy architecture was what moved the needle on regulatory exposure.
Two structural failure modes that no SLA clause can remediate.
The Domain Gap and the Empathy Deficiency account for the majority of insurance outsourcing failures in 2026. Both generate regulatory exposure and policyholder harm that no efficiency saving can offset. Both are auditable before contract execution.
When is insurance outsourcing to the Philippines the wrong fit?
When you want bulk keying at the lowest seat-hour, when there is no core platform such as Guidewire, Duck Creek or Applied Epic to integrate with, or when the work needs a licensed decision. No vetted team adjusts claims, makes coverage determinations or renders underwriting decisions; those stay with your licensed adjusters and underwriters.
The fastest way to become one of the 2026 failure statistics is to force a high-judgment, HITRUST-governed insurance operation into work it was never built for. So before the shortlist, the disqualifiers — ours, stated plainly.
Insurance-literate talent density, ACORD-proficiency screening, and Claims Empathy Specialist protocols do not survive unlimited scale. Vetted partner operations are capped per cluster to guarantee management control, compliance oversight, and the judgment quality the work depends on. If your volume requires more, we architect multiple governed clusters — we do not dilute one.
Why building regulatory architecture before enforcement is insurance’s most undervalued decision.
The NAIC Insurance Data Security Model Law has been adopted in 24 states as of Q2 2026, with enforcement momentum accelerating. Carriers whose Philippine operations already run under NAIC-aligned governance — HITRUST CSF, continuous compliance telemetry, Non-Persistent VDI for all PHI — are not just compliant today. They are positioned ahead of the curve that will force competitors into expensive remediation within 18–24 months.
The moat has commercial value: a carrier demonstrating NAIC-aligned governance wins RFPs from institutional and reinsurance partners who now include data governance in cedent evaluation. Lloyd’s syndicates, global reinsurers and captive managers increasingly require evidence of NAIC-aligned controls in counterparty due diligence.
Underwriting the Back Office — Insurance BPO in the Philippines
An analysis of expense-ratio pressure, policy lifecycle operations, claims and underwriting-support benchmarks, and vendor-selection discipline across carriers, TPAs, and MGAs sourcing in the Philippines. Part of PITON-Global’s Executive White Paper Series, by John Maczynski and Ralf Ellspermann.
Meet the insurers’ BPOs that survived the audit.
Out of the entire Philippine market, only a handful clear every gate we set: the ACORD proficiency audit, the HITRUST CSF certification review, the Claims Empathy Specialist protocol, and a live FNOL accuracy assessment scored on real first-notice calls. The ones that pass carry zero domain gaps and zero empathy deficiency — and those are the only names we hand you.
Get Vendor-Neutral Advice →Our 24-Hour Response Guarantee — a reply within 24 hours, ACORD and HITRUST pre-screen included.
What insurance leaders ask before outsourcing claims and policy admin.
In-depth answers to the questions that decide an insurance BPO engagement — from the principals who run them.
Going deeper on insurance operations
Insurance is one of the most specialized verticals in the market, and this page sits inside our broader guide to outsourcing to the Philippines, which explains how the delivery model works before any single line of business adds its own rules. The pages below are our longer reading on insurance outsourcing, grouped by the decision each one helps a carrier, MGA or broker make. Read them in the order your program will meet them: claims first for most buyers, then the regulatory and seasonal questions, then technology.
Claims, from first notice to settlement
Claims is usually the first queue to move, and the one where a weak vendor does the most damage. Define what the offshore team prepares and what your licensed adjusters decide, write maker-checker points into the SOP, and measure accuracy and leakage before speed. A clean parallel run on your own platform matters more than any benchmark a vendor quotes.
For the operating detail, start with how claims processing and adjudication support is run offshore, then read how digital intake is changing claims handling and the insurtech angle on claims operations.
Life, health and enrollment-season staffing
Life and health books run on a calendar, and staffing has to follow it. Plan the enrollment surge months ahead, keep a trained core team through the quieter months so quality survives the peak, and make sure every agent script has been reviewed against federal marketing rules before the first call.
Our guide to staffing L&H agents beyond the annual enrollment window covers the year-round model, and what is reshaping open-enrollment staffing in 2026 covers the surge itself. When underwriting or claims files are waiting on physician records, see how medical records retrieval teams handle authorizations, provider outreach and complete charts. On the regulatory side, read how CMS and TPMO rules shape a compliant voice operation. Health-adjacent programs should also look at our healthcare hub for the HIPAA and PHI side of the work.
Compliance, governance and continuity
Regulators judge the carrier, not the vendor, so governance has to be something you can evidence on demand. Ask for the audit trail on a live file, confirm how policyholder data is contained, and test the continuity plan before you need it rather than after a typhoon or outage forces the question.
Read the governance model for regulated insurance work first.
Policyholder service and the front office
Servicing is where a carrier’s brand is felt, so train for your tone and products, calibrate QA across every channel, and route sensitive conversations to the people trained to handle them. Our piece on delivering front-office insurance service sets out the model, and how insurance back-office and CX teams are vetted covers the servicing roles, rates and controls behind it.
Technology, AI and risk data
Automation now handles much of the intake and data work, which makes the question where a human must review and who signs. Ask vendors to show that hand-off on a real file, native to your core system, and to explain how exceptions escalate.
How risk assessment support has been rebuilt covers the underwriting side.
Travel and specialty claims
Specialty lines bring their own partners and deadlines. Travel cover sold through booking platforms, for example, needs claims teams that understand both the policy and the trip.
The market and the model
If you are still deciding whether the model fits, four overview pieces set the context: why Manila became a center for insurance operations, how the scope of offshore insurance work has widened, the growth of the sector as a whole and the range of roles Filipino teams now fill for carriers.
What it costs
The rate bands above are the starting point, but the real number depends on your role mix, lines of business and how much of the queue automation absorbs. Our pricing page and savings calculator shows the fully loaded model we use and explains where savings grow and where they flatten.
Choosing a vendor
Many providers claim an insurance vertical; far fewer pass an audit built for one. Our seven-step vendor vetting framework is the method behind every insurance BPO shortlist we build, from scope analytics through forensic diligence to launch governance, and the shortlist is free and carries no obligation. Carriers with banking or lending affiliates can compare notes on the financial services hub.