Financial crime analysts reviewing customer onboarding documents at a desk, representing KYC and AML operations outsourcing to the Philippines
KYC & AML OPERATIONS OUTSOURCING SERVICES PHILIPPINES

Every alert you close late is a regulator’s question waiting. Every one you close wrong is worse.

Customer onboarding and KYC, CDD and EDD, sanctions and PEP screening, transaction-monitoring alert review, periodic refresh and SAR preparation — run by Philippine financial-crime analysts to your procedures with four-eyes QA, so backlogs clear, decisions hold up, and every case file is audit-ready.
Manila, Cebu & Davao delivery SOC 2 Type II / ISO 27001 certified 4-eyes QA · audit-ready case files
PITON-GLOBAL SOURCING · 2026 Q3 2026
Vetted provider shortlist
6–10 providers
Shortlist delivered in
48–72 hrs
Advisory fee to buyers
$0
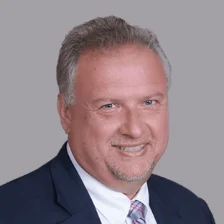
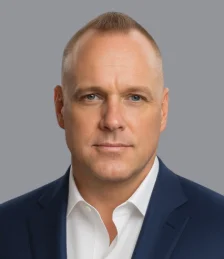
John Maczynski, CEO of PITON-Global Ralf Ellspermann, Founder and CSO of PITON-Global John Maczynski, CEO · Ralf Ellspermann, CSO
Designed for programs scaling from 5 – 500+ FTEs
Backlogs, inconsistent decisions and case files a regulator can’t follow. Get a KYC/AML team that documents like an examiner reads.
PLATFORMS & STANDARDS
ActimizeUnit21ComplyAdvantageFenergoJumio / OnfidoWorld-Check / Dow JonesFATF-aligned4-eyes QA
DECISIONS THAT SURVIVE AN EXAM

Our alert backlog is growing, decisions vary by analyst and our last exam flagged weak case narratives. Can an outsourced KYC/AML team fix this to a regulator’s standard?

Yes, if the team works to your written procedures with independent QA and treats the case narrative as the product. Vetted Philippine financial-crime teams staff certified analysts (CAMS, ICA), run four-eyes review on every decision, write narratives to a template examiners can follow, and report quality alongside throughput.

A WEAK CASE NARRATIVE IS THE REAL COST · 2026

In financial crime operations, a fast decision with a thin narrative fails the exam, triggers a look-back and costs more than the backlog it cleared. KYC/AML here is scored on QA pass rate and narrative quality, then on throughput.

THE CASE LIFECYCLE

Four stations, run for every customer and alert — verify, assess, decide, document.

Financial-crime operations are judged on the file, not the speed.

01 · ONBOARDING & VERIFICATION

Identity and document verification, beneficial-ownership collection, business verification and risk-rating at onboarding, using your IDV tools and procedures. The control: every data point has a source and a timestamp in the file.

GOVERNING METRIC · onboarding accuracy 99%
02 · SCREENING & DUE DILIGENCE

Sanctions, PEP and adverse-media screening with false-positive disposition, CDD for standard risk, EDD with source-of-wealth and source-of-funds for high risk. The control: disposition rationale is written, not ticked.

GOVERNING METRIC · screening dispositions documented, 100%
03 · MONITORING & INVESTIGATION

Transaction-monitoring alert review at L1 and L2, pattern analysis, customer outreach for information, and escalation of suspicious activity. The control: four-eyes review on every close and every escalation.

GOVERNING METRIC · QA pass rate 98%
04 · REPORTING & REFRESH

SAR/STR narrative drafting for your MLRO’s decision, periodic KYC refresh by risk tier, and management information on volumes, quality, aging and typologies.

GOVERNING METRIC · refresh on schedule by risk tier
→ TUNE THE RULES WITH THE EVIDENCEAlert-outcome data shows which rules generate noise and which catch risk. Feeding it back to your monitoring team lowers false positives and lets analysts spend time where it matters.
John Maczynski, CEO of PITON-Global
CEO · REGULATED OPERATIONS

“Regulators don’t read dashboards; they read case files. The teams that do this well write every narrative as if the examiner is reading over their shoulder, because one day they will be. Throughput matters, but only after the file is right.”

John Maczynski · CEO, PITON-Global · 40-Year Global BPO Veteran
CRYPTO & FINTECH KYC

High-volume digital onboarding, wallet and transaction screening, Travel Rule support and rapid scaling for growth-stage platforms. Sector context is on our Blockchain & Crypto and Fintech pages.

BANK & PAYMENTS AML

Alert review, EDD, periodic refresh and remediation programs for banks, payment institutions and lenders, under FinCEN, FCA, AUSTRAC and BSP-aligned procedures. Sector context is on our Banking page.

REMEDIATION & LOOK-BACKS

Surge teams for backlog clearance, regulator-mandated look-backs and KYC remediation, with defined scope, sampling QA and closure reporting. Card and payment fraud review is on our Fraud Detection page.

A CLEARANCE SHOP VS. A FINANCIAL-CRIME OPERATION

A clearance shop vs. an operation whose files survive the exam.

Seven dimensions, read as risk vs. protection.

Analysts
✕Generalists
✓CAMS/ICA-certified, typology-trained
Procedures
✕Improvised
✓Your written procedures, versioned
QA
✕Sampling, if any
✓Four-eyes on every decision
Narratives
✕Tick boxes
✓Examiner-readable, sourced
Metric
✕Alerts closed per hour
✓QA pass rate, then throughput
Escalation
✕Ad hoc
✓Defined thresholds to your MLRO
Feedback
✕None
✓Rule-tuning evidence to your team
RADICAL TRANSPARENCY

You own the risk appetite, the procedures and every SAR decision. We supply analysts and QA — never a filing decision.

01
Your procedures, your risk appetite, your MLRO.

Analysts work to your documented procedures and risk-rating methodology. Suspicious-activity decisions and filings remain with your MLRO or BSA officer; analysts prepare and recommend.

02
Four-eyes is not optional.

Every close, escalation and refresh decision is independently reviewed before it is final. QA results are reported to you weekly, by analyst.

03
Page territory, stated on-page.

Fraud Detection & Mitigation covers transaction and account fraud; Banking, Fintech and Blockchain cover the sectors. This page covers KYC and AML operations as a function.

04
Some cases need in-country handling.

Data-residency rules, certain law-enforcement requests and specific jurisdictions may require onshore analysts. We identify them in scoping.

A shortlist that includes “no” is the only kind worth having.
FOR COMPLIANCE, RISK & OPERATIONS LEADERS If an examiner picked twenty of your case files at random tomorrow, how many would you be happy with?
PRICING TOPOGRAPHY · 2026 RATE CARD

Indicative 2026 rates — priced by role, fully loaded per hour.

CORE ROLERATE (USD/HR)OPERATIONAL PROFILETIER
KYC onboarding analyst$8–$12IDV, document review, risk rating.R
Screening analyst (sanctions / PEP)$8–$12Hit disposition with written rationale.R
Periodic refresh analyst$8–$12Risk-tiered KYC refresh and outreach.R
L1 transaction-monitoring analyst$8–$12Alert triage and disposition.R
L2 investigator / EDD analyst$10–$12Complex investigations, source of wealth and funds.C
SAR/STR drafting specialist$14–$18Examiner-readable narratives for your MLRO — the skill clearance shops lack.NO GENERIC
EQUIVALENT
Crypto / blockchain analytics investigator$14–$18Chainalysis / TRM tracing and wallet risk.NO GENERIC
EQUIVALENT
QA reviewer (CAMS / ICA)$10–$12Four-eyes review, calibration, quality reporting.QUALITY
Financial-crime team manager$10–$12Procedure governance, MI, regulator-facing support.LEADERSHIP

Per-alert and per-case pricing available for backlog and remediation programs. Rates confirmed per engagement.

Scope my KYC/AML program →
GOVERNED TO FINANCIAL-CRIME STANDARDS

BSA/AML, FinCEN and OFAC (US) · FCA and MLR 2017 (UK) · AUSTRAC (Australia) · BSP and AMLC (Philippines) · FATF recommendations and Travel Rule for virtual assets · SOC 2 Type II / ISO 27001 — certified · GDPR, RA 10173 for customer data · Data residency assessed per jurisdiction.

FOR COMPLIANCE & AUDITEvery case carries its evidence, rationale, reviewer and timestamps in your case-management system — nothing is reconstructed for the exam.
8-WEEK KYC/AML STAND-UP

A financial-crime team live in 8 weeks — procedures and QA in place before the first alert is closed.

A gated stand-up. Analysts close cases only after passing procedure certification and a calibration round reviewed by your compliance team.

Wk 1–2
Procedures & Access
Your procedures, risk methodology and escalation thresholds documented and versioned; case-management and screening tool access set up.
Wk 3–4
Certification & Calibration
Analysts trained and tested on your procedures; calibration cases reviewed with your MLRO; QA templates agreed.
Wk 5–6
Supervised Production
Cases worked with 100% QA and daily feedback; quality reported by analyst.
Wk 7–8
Scale & Govern
Volume ramps under weekly quality, aging and typology MI; rule-tuning evidence starts flowing.
THE FILE TEST · WHAT TO VERIFY

Before a vendor closes your alerts, can they show you a case file you’d hand to an examiner?

Three checks separate a financial-crime operation from a clearance shop.

01
Sample Case Files
Ask for redacted case files from a live client and read the narratives yourself.
VERIFY: Request redacted sample files
02
QA Model and Results
Ask whether QA is four-eyes on every decision or sampled, and for pass rates by analyst.
VERIFY: Request QA methodology and results
03
Certifications and Tenure
Ask how many analysts hold CAMS or ICA and how long they have been on financial-crime work.
VERIFY: Request certification and tenure data
THE EXAM-READY ARCHITECTUREhow each risk is designed out
Procedures, Versioned
Analysts work to your written procedures, and every version is retained.
Four-Eyes, Always
No decision is final without independent review.
Narratives, Sourced
Every rationale cites its evidence and reads clearly to an outsider.
Ralf Ellspermann, Founder and CSO of PITON-Global
CSO · REGULATED OPERATIONS

“Ask a prospective KYC/AML partner to walk you through one closed alert, start to finish, from their case system. If you cannot follow why it was closed without them explaining, neither will the examiner.”

Ralf Ellspermann · CSO, PITON-Global · 25-Year Philippine BPO Veteran
FOR COMPLIANCE, RISK & FINANCIAL-CRIME LEADERS

Clear the backlog. Keep the quality. Pass the exam.

Tell us your volumes, tools and jurisdictions, and we’ll hand you 6–10 vetted Philippine KYC/AML providers, every one assessed on case-file quality and QA results.

Book Your Free Call →
Vendor-neutral · no cost to you · 24-hour response guarantee, sample file review included · prepared and presented by John Maczynski, CEO
ANSWERED BY OUR PRINCIPALS

The questions compliance teams ask before outsourcing KYC and AML operations.

Straight answers from the two principals accountable for each engagement.

What KYC and AML work can be outsourced?+
Customer onboarding and identity verification, CDD and EDD, sanctions, PEP and adverse-media screening, transaction-monitoring alert review, periodic refresh, remediation and look-backs, and SAR/STR narrative drafting. Filing decisions stay with your MLRO.— John Maczynski, CEO
Is it acceptable to regulators to outsource AML operations?+
Yes, in most jurisdictions, provided the regulated firm retains oversight, decision authority and access to records, and the arrangement is documented and risk-assessed. Many banks and fintechs run this model; we help structure it to your regulator’s outsourcing guidance.— John Maczynski, CEO
Are the analysts certified?+
Team leads and QA reviewers are CAMS or ICA certified, and analysts are trained and tested on your procedures and typologies before working live cases.— Ralf Ellspermann, CSO
Which tools do your teams work in?+
Actimize, Unit21, ComplyAdvantage, Fenergo, Jumio, Onfido, World-Check, Dow Jones, Chainalysis and TRM, in your instance so case files stay in your system of record.— Ralf Ellspermann, CSO
How is quality controlled?+
Four-eyes review on every decision, narrative templates aligned to examiner guidance, weekly QA reporting by analyst, and calibration sessions with your compliance team.— Ralf Ellspermann, CSO
Can you clear a backlog quickly?+
Yes. Surge teams of 30–80 analysts can stand up in six to eight weeks and clear tens of thousands of alerts, with the same QA standard as steady state.— John Maczynski, CEO
Do you handle crypto and Travel Rule requirements?+
Yes. Analysts trained on blockchain analytics tools review wallet risk, trace transactions and support Travel Rule data exchange for exchanges and custodians.— Ralf Ellspermann, CSO
What about data residency?+
Some jurisdictions restrict where customer data may be processed. We assess this in scoping and, where needed, design a split model with onshore handling for restricted data.— John Maczynski, CEO
How is KYC/AML outsourcing priced?+
Per analyst hour ($10–$18 by role), or per alert or per case for backlog and remediation programs once volumes are defined.— John Maczynski, CEO
What does KYC/AML outsourcing cost in the Philippines?+
Indicative 2026 rates run from about $8 to $18 per hour by role, or roughly $3–$5 per L1 alert fully loaded, against $10–$14 onshore.— John Maczynski, CEO
Authorship, Review & Benchmark Verification
Authored by:
Ralf Ellspermann, Founder and CSO of PITON-Global
Ralf Ellspermann
Chief Strategy Officer of PITON-Global
Two Decades Building and Advising Award-Winning Philippine BPO Operations

Ralf benchmarks financial-crime operations on case-file quality, QA model and analyst certification.

View full bio  →
Verified by:
John Maczynski, CEO of PITON-Global
John Maczynski
CEO of PITON-Global
Former Global EVP of the World’s Largest Contact Center · Four Decades of Outsourcing Experience

John reviews the outsourcing governance and commercial terms behind each KYC/AML program on this page.

View full bio  →
Last Reviewed & Verified · September 28, 2026

Re-audited as FinCEN, FCA, AUSTRAC, BSP and FATF guidance changes. Every benchmark on this page is held to PITON-Global’s internal vetting standard.

Inquire Now