
55% of fintech outsourcing partnerships fail within 18 months — what should we audit before we sign?
Three failure modes, each testable in diligence: AI-washing (ask for the named platform and governance docs — 68% of “AI-powered” providers audited in Q2 2026 couldn’t name their LLM); generic hiring (ask for the analyst interview questions); shared infrastructure (run a live VDI and session-isolation test). the Southeast Asian neobank on that architecture: ATO detection 65% to 95%+, onboarding 36 hours to 48 minutes.
BPO Suppliers
Clients Served
Delivering for Clients
The “move fast and break things” era of fintech is over. Outsourcing is no longer judged by cost per seat, but by risk containment, regulatory alignment and the ability to deploy Agentic AI that executes high-complexity financial workflows with 100% auditability — at 55–65% lower total cost than in-house builds.
Fintechs follow a clear outsourcing path: support, then KYC, then payments and lending. Here it is.
Why do the fastest-scaling fintechs outsource their most complex workflows — not their simplest?
Because the workflows breaking fintechs in 2026 are judgment-critical — they demand Agentic AI plus a finance-literate human layer, not cheap labor. Fintechs are not short on ideas — they are short on certainty. The workflows breaking them are judgment-critical: a 2AM cross-border settlement that fails validation at the Adyen gateway, an account-takeover that replicates the victim’s device fingerprint, an AI-generated advice response that is accurate but regulatorily non-compliant. These are Intelligence Arbitrage problems.
Intelligence Arbitrage is an operational BPO model that combines Agentic AI systems with finance-literate human specialists to execute high-complexity financial workflows. The model measures performance by value per completed workflow rather than hourly cost per seat, prioritizing risk containment, compliance, and regulatory alignment.
“Fintech outsourcing is no longer evaluated by cost per seat, but by risk containment, regulatory alignment, and the ability to deploy Agentic AI that executes high-complexity financial workflows with 100% auditability.”
What are the four pillars of institutional-grade fintech governance?
Agentic Payment Ecosystems, the Regulatory Sovereignty Layer, the Linguistic Guardian Protocol and Forensic Fraud Orchestration. Each layer is independently valuable. Together they form a hardened operational architecture that scales without regulatory exposure — stress-tested under live client conditions, not retrofitted to them.
The right operation depends on your product, your regulators, and where your fraud concentrates.
High-velocity onboarding is where synthetic identity hides. Sub-hour biometric-OCR KYC, behavioral-biometrics ATO defense, and compliance-aware support that scales with your user curve — not against it.
Origination cycles are conversion cycles. Document indexing, credit decision support, and collections operations that compress time-to-funded — with underwriters owning every final call.
The 2AM cross-border settlement that fails validation at the gateway is your problem whether you’re awake or not. 24/7 agentic settlement coverage, real-time reconciliation, dispute and chargeback operations inside Stripe, Adyen, Mambu and Temenos.
Travel-rule and AML screening, transaction monitoring, and GENIUS Act–aligned compliance operations for exchanges and digital-asset platforms — where a governance gap is a licensing event.
Labor arbitrage vs. Intelligence Arbitrage.
The competitive delta between a legacy 2024 BPO baseline and the PITON-Global-vetted 2026 standard — across seven performance dimensions that determine resilience, valuation and regulatory standing.
Where does the 8–9× return come from — and why does the CFO model miss 60%?
From four value streams the standard cost model omits: fraud recovery, onboarding conversion, retention and 24/7 coverage. The standard cost-comparison model captures, at most, 40% of the economic impact. The remaining 60% sits in four value streams typically attributed to product, marketing or “market conditions” rather than operational architecture quality.
ROI figures reflect 12-month measured net benefit against total engagement cost on 50-agent-equivalent deployments, per the audit methodology in Section 4 of the 2026 report.
Less engagement cost ($1.05M)
Shutting down synthetic-identity fraud at onboarding — a smaller deployment, a representative result.
Not every engagement is a four-pillar Hardened Shield build. A single-pillar deployment against a single failure surface returned a measurable delta in one quarter — speed from the agents, accuracy from the analysts. The architecture scales down as cleanly as it scales up.
Where does 55–65% actually come from? Run your own numbers.
The ROI model above is the top-down view. This is the bottom-up one — fully-loaded cost per fintech-operations FTE, by delivery model, at your team size. No blended averages, no footnote games.
Illustrative projection at standard role mix. Savings on a 50-agent-equivalent program run 55–65% below an in-house build, 62% at standard role mix — depending on the ratio of judgment-critical roles (compliance, fraud) to volume roles (support, back-office). This table is the cost line only; the four value streams above sit on top of it. The seat was never the expensive part of fintech. The miss is.
Indicative 2026 Philippine sourcing rates — by role, not by blend.
Blended rates hide the thing that matters: whether you are paying volume prices for judgment-critical work, or judgment prices for volume work. These are the indicative hourly bands across PITON-Global-vetted providers, Q2 2026.
Rates reflect finance-literate, IQ- and integrity-screened profiles — not generic call-center benches. A quote materially below these bands is usually the first auditable sign of Generic Hiring (see failure modes above).
Price my exact role mix →A fully institutional-grade operation in 12 weeks — without regulatory exposure.
A structured, phase-gated roadmap. Each gate requires sign-off before progression — no client enters Full Migration before CSAT ≥85% and fraud detection ≥90% are confirmed in Soft Launch.
What drives the 55% fintech outsourcing partnership failure rate?
Three structural failure modes — AI-washing, generic hiring and shared infrastructure — each auditable before you sign. Fifty-five percent of partnerships fail within 18 months (PITON-Global engagement audits, 2024–2026), and these failures are not random.
“Forty years in this industry teaches you to distrust a polished pitch. The two things I refuse to overlook are shared infrastructure and an analyst bench that has never been interrogated live. The 55% that fail mistook a demo for an operation.”
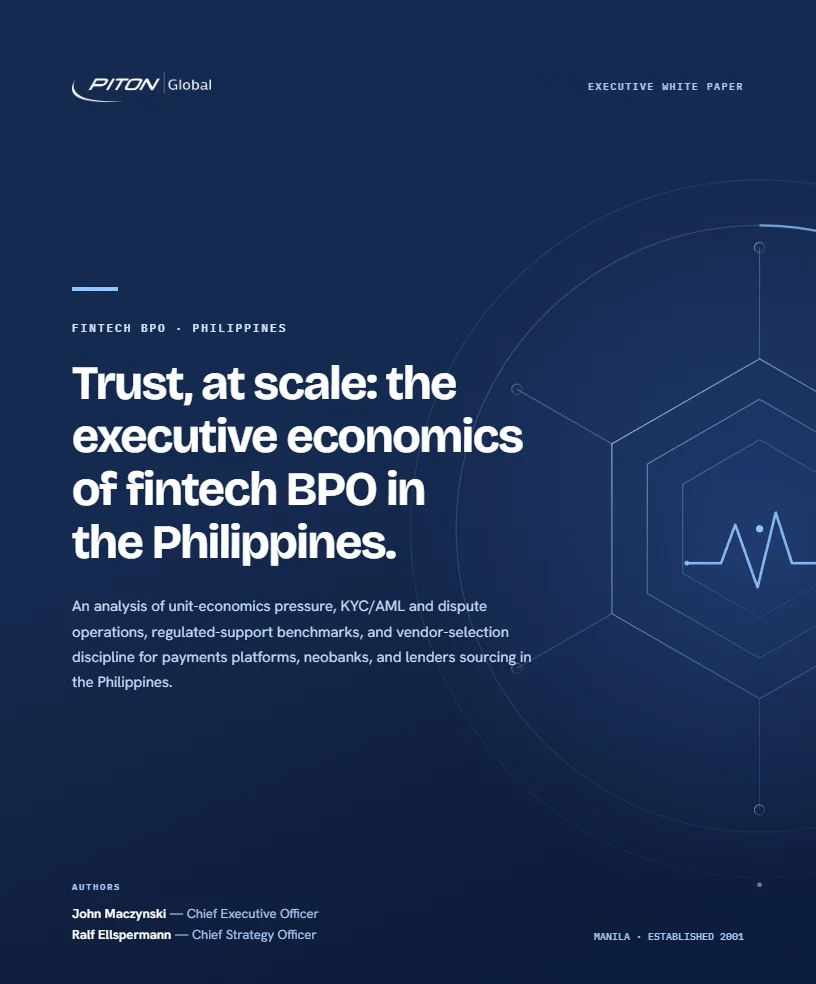
Trust, at Scale — Fintech BPO in the Philippines
An analysis of unit-economics pressure, KYC/AML and dispute operations, regulated-support benchmarks, and vendor-selection discipline for payments platforms, neobanks, and lenders sourcing in the Philippines. Part of PITON-Global’s Executive White Paper Series, by John Maczynski and Ralf Ellspermann.
Independent coverage. Third-party validation.
What fintech leaders ask before outsourcing risk and support.
In-depth answers to the questions that decide a fintech BPO engagement — from the principals who run them.

Going deeper on fintech operations
Fintech sits inside a wider regulated-finance market, and our financial services outsourcing hub covers the banking, lending, insurance and payments work around it, so you can see where a digital-first operation borrows from the incumbents and where it has to differ. Our fintech outsourcing strategy guide walks through all eighteen functions a digital-first finance company can hand to an offshore team, from KYC and fraud to QA and release support, and it is the complete index for that cluster. The notes below pick the starting points by decision, and add the wider reading on support, growth and automation that the guide does not cover.
Onboarding, identity and fraud
Onboarding is where growth and risk collide: every friction point costs sign-ups, and every gap lets synthetic identities through. Before you compare vendors, decide which verification decisions a person must make, which a model may make alone, and how quickly a flagged case must be cleared. Our note on handling the KYC compliance surge and the guide to fraud detection and mitigation are the best starting points. For the supervisory side, read how regulators are adopting their own technology, why anti-money-laundering work still needs human-led AI rather than automation alone, and what US and UK regulators now expect from a delivery partner. The planned financial compliance and risk hub will gather the control framework in one place.
Payments, disputes and money movement
Payment operations fail quietly, in settlement breaks and aging disputes, long before a customer complains. Ask each candidate how they reconcile across processors, how a chargeback is evidenced and who owns the deadline. Our notes on global settlement and payments operations and on dispute and chargeback management set out the controls. Wallets, processors and card programs will get their own treatment in the planned payments and wallet support hub.
Customer and technical support
Fintech users expect an answer inside the app, at any hour, from someone who understands the product and the rules around it. Hire for product literacy first, then build compliance-aware scripts and a fast path from support to fraud and engineering. Our guides to scaling trustworthy customer service and to technical support that closes the product-trust gap cover the two desks most fintechs build first.
Finance operations and cost discipline
Behind the app sits a finance function that has to close, reconcile and report with a small team. Keep policy and sign-off in-house and give the offshore team clearly scoped processing beneath it. Our note on financial integrity in fintech finance operations covers the work itself.
Growth, automation and what comes next
The fastest-growing fintechs use their offshore teams to enter new markets and to run AI safely, not only to cut cost. Ask vendors where their people sit in the automation loop and how they handle a model decision a customer disputes.
Costing the team and choosing the vendor
The rate table on this page lists roles one by one; our pricing page shows how a fully loaded seat is built and lets you model a team size. When you are ready to compare vendors, our seven-step vendor vetting framework covers forensic diligence, security audit and workflow stress-testing, the steps that matter most when a vendor will touch customer funds and identity data.
55% of fintech outsourcing partnerships fail within 18 months — what should we audit before we sign?
Three failure modes, each testable in diligence: AI-washing (ask for the named platform and governance docs — 68% of “AI-powered” providers audited in Q2 2026 couldn’t name their LLM); generic hiring (ask for the analyst interview questions); shared infrastructure (run a live VDI and session-isolation test). the Southeast Asian neobank on that architecture: ATO detection 65% to 95%+, onboarding 36 hours to 48 minutes.
BPO Suppliers
Clients Served
Delivering for Clients
The “move fast and break things” era of fintech is over. Outsourcing is no longer judged by cost per seat, but by risk containment, regulatory alignment and the ability to deploy Agentic AI that executes high-complexity financial workflows with 100% auditability — at 55–65% lower total cost than in-house builds.
Fintechs follow a clear outsourcing path: support, then KYC, then payments and lending. Here it is.
Why do the fastest-scaling fintechs outsource their most complex workflows — not their simplest?
Because the workflows breaking fintechs in 2026 are judgment-critical — they demand Agentic AI plus a finance-literate human layer, not cheap labor. Fintechs are not short on ideas — they are short on certainty. The workflows breaking them are judgment-critical: a 2AM cross-border settlement that fails validation at the Adyen gateway, an account-takeover that replicates the victim’s device fingerprint, an AI-generated advice response that is accurate but regulatorily non-compliant. These are Intelligence Arbitrage problems.
Intelligence Arbitrage is an operational BPO model that combines Agentic AI systems with finance-literate human specialists to execute high-complexity financial workflows. The model measures performance by value per completed workflow rather than hourly cost per seat, prioritizing risk containment, compliance, and regulatory alignment.
“Fintech outsourcing is no longer evaluated by cost per seat, but by risk containment, regulatory alignment, and the ability to deploy Agentic AI that executes high-complexity financial workflows with 100% auditability.”
What are the four pillars of institutional-grade fintech governance?
Agentic Payment Ecosystems, the Regulatory Sovereignty Layer, the Linguistic Guardian Protocol and Forensic Fraud Orchestration. Each layer is independently valuable. Together they form a hardened operational architecture that scales without regulatory exposure — stress-tested under live client conditions, not retrofitted to them.
The right operation depends on your product, your regulators, and where your fraud concentrates.
High-velocity onboarding is where synthetic identity hides. Sub-hour biometric-OCR KYC, behavioral-biometrics ATO defense, and compliance-aware support that scales with your user curve — not against it.
Origination cycles are conversion cycles. Document indexing, credit decision support, and collections operations that compress time-to-funded — with underwriters owning every final call.
The 2AM cross-border settlement that fails validation at the gateway is your problem whether you’re awake or not. 24/7 agentic settlement coverage, real-time reconciliation, dispute and chargeback operations inside Stripe, Adyen, Mambu and Temenos.
Travel-rule and AML screening, transaction monitoring, and GENIUS Act–aligned compliance operations for exchanges and digital-asset platforms — where a governance gap is a licensing event.
Labor arbitrage vs. Intelligence Arbitrage.
The competitive delta between a legacy 2024 BPO baseline and the PITON-Global-vetted 2026 standard — across seven performance dimensions that determine resilience, valuation and regulatory standing.
Where does the 8–9× return come from — and why does the CFO model miss 60%?
From four value streams the standard cost model omits: fraud recovery, onboarding conversion, retention and 24/7 coverage. The standard cost-comparison model captures, at most, 40% of the economic impact. The remaining 60% sits in four value streams typically attributed to product, marketing or “market conditions” rather than operational architecture quality.
ROI figures reflect 12-month measured net benefit against total engagement cost on 50-agent-equivalent deployments, per the audit methodology in Section 4 of the 2026 report.
Less engagement cost ($1.05M)
Shutting down synthetic-identity fraud at onboarding — a smaller deployment, a representative result.
Not every engagement is a four-pillar Hardened Shield build. A single-pillar deployment against a single failure surface returned a measurable delta in one quarter — speed from the agents, accuracy from the analysts. The architecture scales down as cleanly as it scales up.
Where does 55–65% actually come from? Run your own numbers.
The ROI model above is the top-down view. This is the bottom-up one — fully-loaded cost per fintech-operations FTE, by delivery model, at your team size. No blended averages, no footnote games.
Illustrative projection at standard role mix. Savings on a 50-agent-equivalent program run 55–65% below an in-house build, 62% at standard role mix — depending on the ratio of judgment-critical roles (compliance, fraud) to volume roles (support, back-office). This table is the cost line only; the four value streams above sit on top of it. The seat was never the expensive part of fintech. The miss is.
Indicative 2026 Philippine sourcing rates — by role, not by blend.
Blended rates hide the thing that matters: whether you are paying volume prices for judgment-critical work, or judgment prices for volume work. These are the indicative hourly bands across PITON-Global-vetted providers, Q2 2026.
Rates reflect finance-literate, IQ- and integrity-screened profiles — not generic call-center benches. A quote materially below these bands is usually the first auditable sign of Generic Hiring (see failure modes above).
Price my exact role mix →A fully institutional-grade operation in 12 weeks — without regulatory exposure.
A structured, phase-gated roadmap. Each gate requires sign-off before progression — no client enters Full Migration before CSAT ≥85% and fraud detection ≥90% are confirmed in Soft Launch.
What drives the 55% fintech outsourcing partnership failure rate?
Three structural failure modes — AI-washing, generic hiring and shared infrastructure — each auditable before you sign. Fifty-five percent of partnerships fail within 18 months (PITON-Global engagement audits, 2024–2026), and these failures are not random.
“Forty years in this industry teaches you to distrust a polished pitch. The two things I refuse to overlook are shared infrastructure and an analyst bench that has never been interrogated live. The 55% that fail mistook a demo for an operation.”
Trust, at Scale — Fintech BPO in the Philippines
An analysis of unit-economics pressure, KYC/AML and dispute operations, regulated-support benchmarks, and vendor-selection discipline for payments platforms, neobanks, and lenders sourcing in the Philippines. Part of PITON-Global’s Executive White Paper Series, by John Maczynski and Ralf Ellspermann.
Independent coverage. Third-party validation.
What fintech leaders ask before outsourcing risk and support.
In-depth answers to the questions that decide a fintech BPO engagement — from the principals who run them.
Going deeper on fintech operations
Fintech sits inside a wider regulated-finance market, and our financial services outsourcing hub covers the banking, lending, insurance and payments work around it, so you can see where a digital-first operation borrows from the incumbents and where it has to differ. Our fintech outsourcing strategy guide walks through all eighteen functions a digital-first finance company can hand to an offshore team, from KYC and fraud to QA and release support, and it is the complete index for that cluster. The notes below pick the starting points by decision, and add the wider reading on support, growth and automation that the guide does not cover.
Onboarding, identity and fraud
Onboarding is where growth and risk collide: every friction point costs sign-ups, and every gap lets synthetic identities through. Before you compare vendors, decide which verification decisions a person must make, which a model may make alone, and how quickly a flagged case must be cleared. Our note on handling the KYC compliance surge and the guide to fraud detection and mitigation are the best starting points. For the supervisory side, read how regulators are adopting their own technology, why anti-money-laundering work still needs human-led AI rather than automation alone, and what US and UK regulators now expect from a delivery partner. The planned financial compliance and risk hub will gather the control framework in one place.
Payments, disputes and money movement
Payment operations fail quietly, in settlement breaks and aging disputes, long before a customer complains. Ask each candidate how they reconcile across processors, how a chargeback is evidenced and who owns the deadline. Our notes on global settlement and payments operations and on dispute and chargeback management set out the controls. Wallets, processors and card programs will get their own treatment in the planned payments and wallet support hub.
Customer and technical support
Fintech users expect an answer inside the app, at any hour, from someone who understands the product and the rules around it. Hire for product literacy first, then build compliance-aware scripts and a fast path from support to fraud and engineering. Our guides to scaling trustworthy customer service and to technical support that closes the product-trust gap cover the two desks most fintechs build first.
Finance operations and cost discipline
Behind the app sits a finance function that has to close, reconcile and report with a small team. Keep policy and sign-off in-house and give the offshore team clearly scoped processing beneath it. Our note on financial integrity in fintech finance operations covers the work itself.
Growth, automation and what comes next
The fastest-growing fintechs use their offshore teams to enter new markets and to run AI safely, not only to cut cost. Ask vendors where their people sit in the automation loop and how they handle a model decision a customer disputes.
Costing the team and choosing the vendor
The rate table on this page lists roles one by one; our pricing page shows how a fully loaded seat is built and lets you model a team size. When you are ready to compare vendors, our seven-step vendor vetting framework covers forensic diligence, security audit and workflow stress-testing, the steps that matter most when a vendor will touch customer funds and identity data.