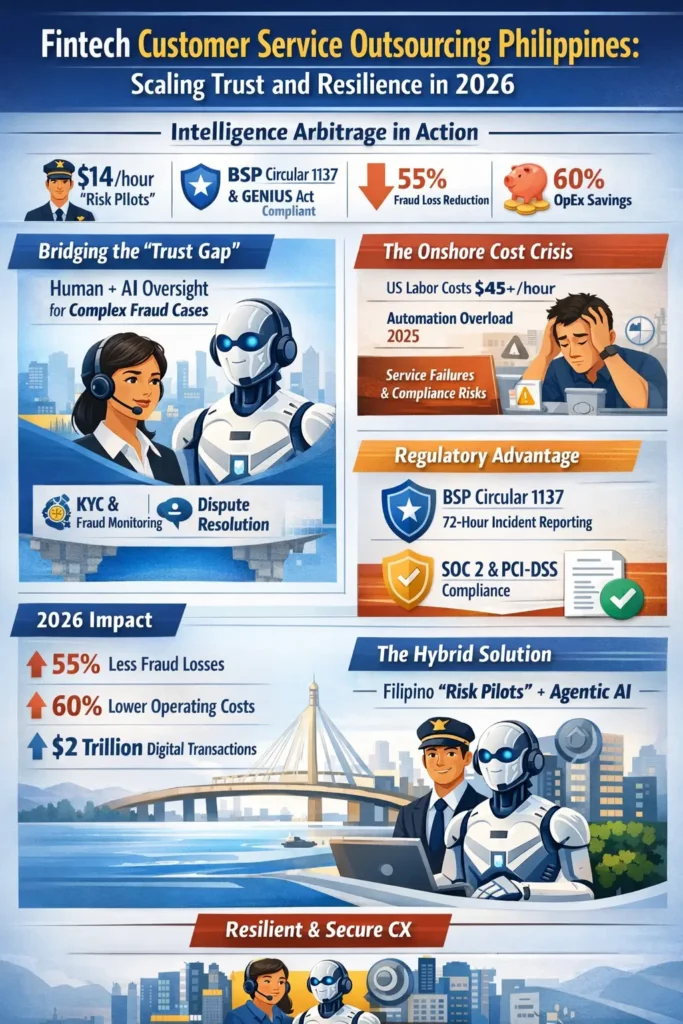
In 2026, fintech customer service outsourcing to the Philippines has evolved from labor arbitrage into “Intelligence Arbitrage.” Leading neobanks use a fully loaded $14/hour benchmark to deploy specialized Filipino “Risk Pilots” who manage fleets of Agentic AI and staff the payment support and fraud screening for neobanks that digital lenders and wallets depend on. This hybrid model is built for BSP Circular 1137 and, for stablecoin platforms, the GENIUS Act, resolving the “Trust Gap” by providing human-in-the-loop (HITL) oversight for complex fraud and regulatory exceptions. The result is lower fraud losses and a structural OpEx advantage over onshore operations.
How Neobanks and Payments Leaders Use “Intelligence Arbitrage” to Outperform Legacy Finance
Executive Summary: The Resilience Mandate
The fintech landscape of 2026 is no longer defined by rapid user acquisition; it is defined by operational resilience. As digital transaction volumes hit the $2 trillion milestone, the “trust gap”—the distance between a digital-first promise and a failed service delivery—has become the primary driver of churn. According to current 2026 market analytics, customer acquisition costs (CAC) have spiked 30% due to heightened competition and regulatory pressure.
Against this high-stakes backdrop, the Philippine BPO sector has evolved into a strategic hub for “Intelligence Arbitrage.” By leveraging a specialized workforce in Manila and Davao, global fintech leaders are engineering “Agentic Hybrid” systems—where autonomous AI handles the transaction, but specialized Filipino “Risk Pilots” protect the brand, the license, and the customer.
The Fintech “Trust Gap”: Why Service is the New Moat
In 2026, fintech products are commoditized. Features like instant transfers and fractional investing are now table stakes. The true differentiator is how a brand responds when things go wrong. In digital finance, “service is the product.”
The Onshore Compliance Crisis
With US-based fintech operations costs now exceeding $45.00/hour for regulated roles, many firms over-indexed on “automation-only” models in 2025. This created a “Service Desert” where users were trapped in infinite chatbot loops during critical moments, such as account freezes or suspected Deepfake Voice Fraud.
The Philippines provides the only global ecosystem where PCI-DSS 4.0.1 and SOC 2 Type II standards meet a workforce with deep financial intuition. At the Manila benchmark rate, fintechs can afford to put a human “Risk Pilot” behind every high-value interaction, ensuring that “hyper-efficiency” never comes at the cost of “hyper-frustration.”
2026 Functional Execution Matrix: AI vs. Human Value-Add
| Function | AI Role (Agentic Automation) | The Human Value-Add (Manila) | Strategic Impact |
| KYC/Onboarding | Biometric OCR & liveness checks. | Manual triage of “edge case” ID & PEP alerts. | Sub-hour onboarding; 99% accuracy. |
| Fraud Monitoring | Real-time anomaly detection via ML. | Live investigation of “high-confidence” alerts. | 40–55% lower fraud loss. |
| Dispute Resolution | Policy-led triage & data gathering. | Expert representation in complex arbitration. | 22% increase in recovery rates. |
| Stablecoin Ops | On-chain ledger reconciliation. | Reserve transparency & GENIUS Act audits. | Regulatory Safe Harbor. |
2026 Case Study: The “Zero-Day” Fraud Shield
The Challenge: In Q1 2026, a mid-sized Neobank faced a sophisticated “AI-Cloned Voice” attack targeting high-net-worth users. Their automated AI filters were flagging 30% of legitimate users as false positives, while their domestic US team was unable to keep up with the manual review backlog.
The Solution: The bank partnered with PITON-Global to deploy a Forensic Risk Pod in Manila.
- The Strategy: The team implemented “Agentic Sifting,” where AI handled the bulk of basic KYC, but any “Model Doubt” (an anomaly score above the agreed threshold) was instantly routed to a Manila-based specialist.
- The Execution: These “Risk Pilots” utilized real-time behavioral telemetry to spot “human-in-the-middle” attacks that AI couldn’t detect, the approach laid out in our fintech fraud detection and mitigation playbook.
- The Results:
- Fraud Loss: Reduced sharply in the first year.
- Onboarding Friction: False positives fell to a fraction of the pre-launch rate, a core goal of trust-first customer and merchant onboarding.
- NPS Surge: Trust scores rose markedly due to empathetic human intervention during fraud attempts.
Regulatory Rigor: BSP Circular 1137 & The “Compliance Moat”
A defining advantage of Manila’s 2026 delivery hubs is their alignment with global “bank-grade” regulations.
- BSP Circular 1137: The central bank mandates that outsourcing partners meet the same cybersecurity and IT risk standards as the banks themselves.
- The 72-Hour Mandate: Adherence to the 2026 SEC Cyber Resilience Framework requires material incident disclosure within a 72-hour window. Philippine centers now operate as “Biometric Clean Rooms,” where PII (Personally Identifiable Information) is masked at the edge and never resides on local hardware.
Strategic Insights: 2026 Fintech CX Architecture
Q: Can a $14/hour agent handle complex AML and sanctions screening? Ralf Ellspermann: Absolutely. In 2026, the $14 rate in the Philippines attracts ACAMS-certified professionals. We aren’t hiring generalists; we are hiring financial professionals who navigate OFAC and UN lists with surgical precision. This allows fintechs to maintain “Tier-1” compliance rigor while operating at “startup” costs.
Q: How do you manage the risk of “Account Takeovers” in an offshore environment? John Maczynski: We deploy Cryptographic Device Binding. In 2026, an offshore agent never sees a customer’s raw credentials. Every action is tied to a unique transaction token. Our “Zero-Trust Sovereign Perimeter” ensures that even if an agent’s terminal were compromised, the data remains encrypted at the edge.
Final Verdict: The 2026 Executive Mandate
As John Maczynski, CEO of PITON-Global, summarizes:
“Fintech brands are not just competing on code; they are competing on Trust. Trust is the most expensive asset a brand owns, yet it’s the easiest to break. The Philippines offers the only scalable way to protect that asset at a discount. If your BPO isn’t talking about Predictive Fraud Mitigation, they are managing your decline.”